Fifteen rental nights. That’s the whole budget a luxury second-home owner has before the IRS stops treating the property as a private residence and starts treating it as a business. Most buyers don’t learn the line exists until their accountant finds it the following April.
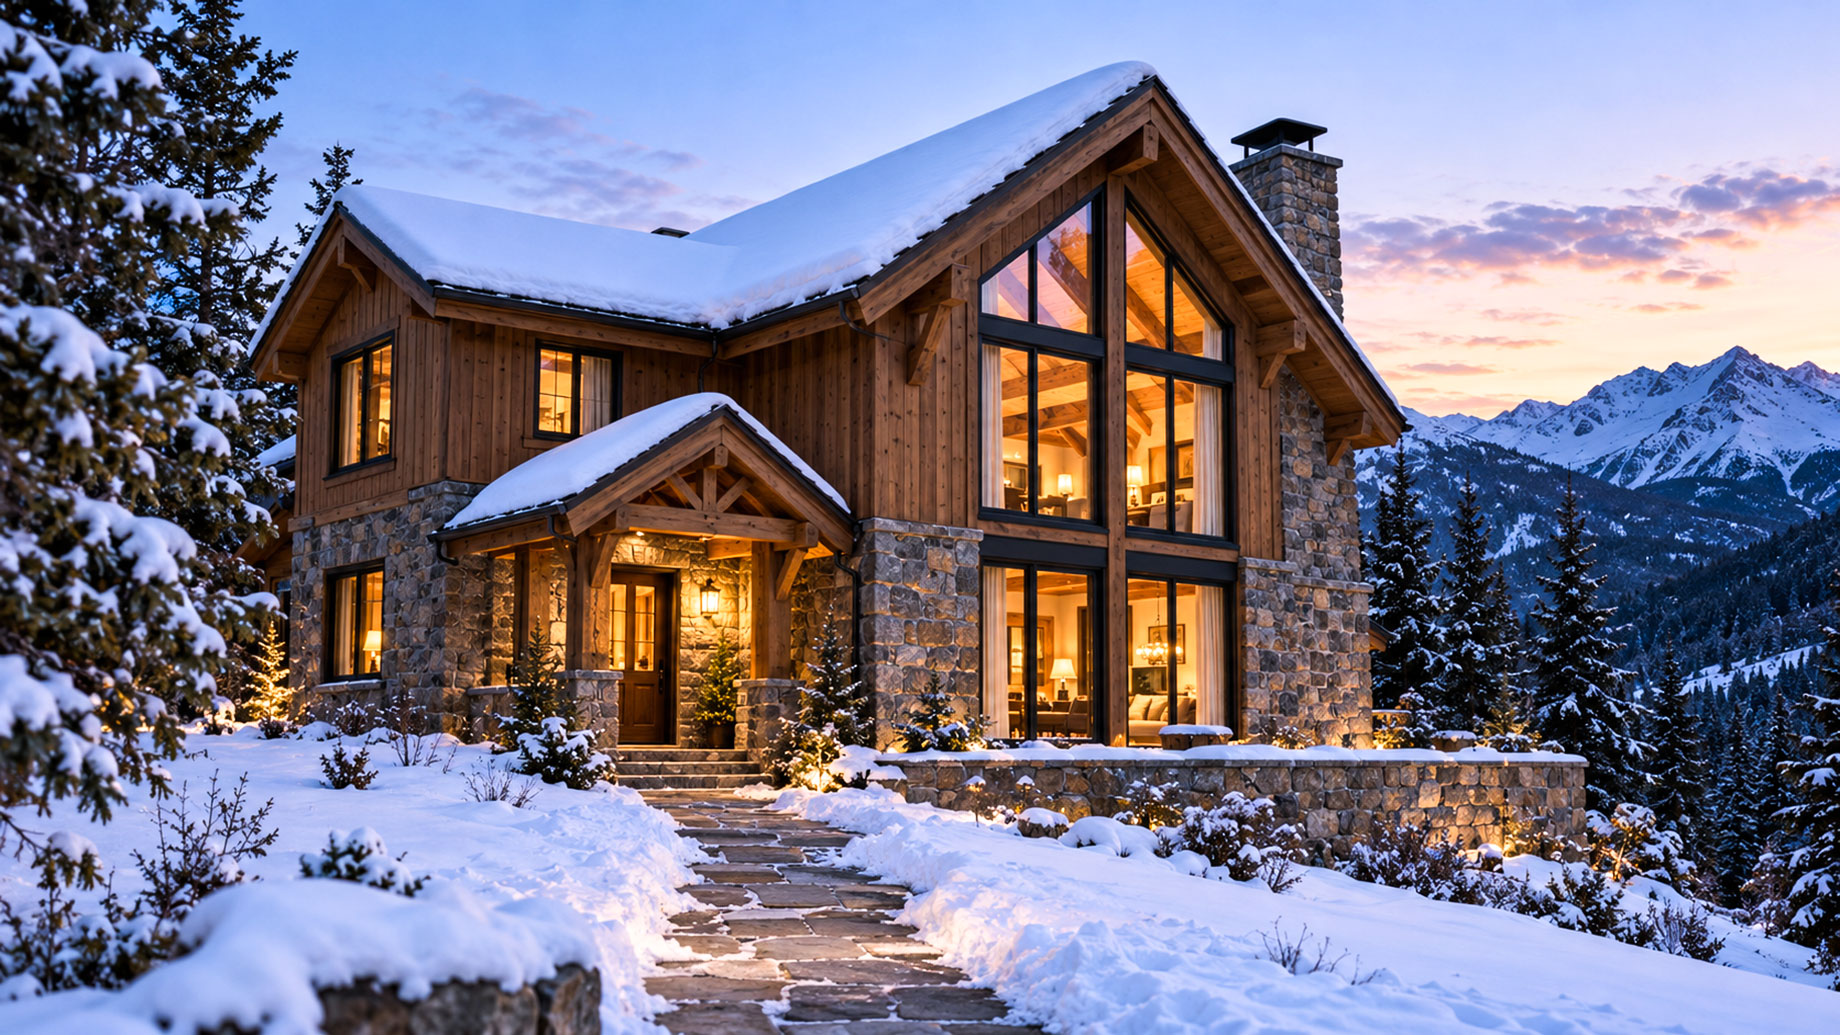
A vacation home that pays for itself is an easy sell. A ski-in chalet, a beachfront villa, a lake house with a dock, rented through a concierge platform when the family isn’t using it, generating five figures a season and offsetting the mortgage.
The brochure reads like a lifestyle upgrade with a bonus revenue line. The tax code reads it as three different properties depending on how the calendar fills in, and the one the owner ends up with is rarely the one they planned on.
The 15-Night Line Changes Everything
Picture the chalet rented for 14 nights over the holidays at a strong nightly rate, with the owner using it personally the rest of the year. Under IRS Topic 415, that income doesn’t get reported at all. The dwelling counts as a residence, not a rental, and the rent is excluded from gross income entirely.
Rent it for a 15th night and the character of the property flips. Every dollar of rental income becomes reportable, the IRS wants it on Schedule E, and the owner inherits a new set of rules that didn’t apply the day before. One night – that’s the whole difference.
The temptation is to work backward from the number, figuring out what the property can earn and letting that drive the rental calendar. The temptation is also where the trouble starts. Luxury buyers who want a clean read on how this plays out often bring in a specialized tax advisor before the first guest books, because the 15th night is almost always a decision rather than an accident.
Cross the Line and the Deductions Follow
Say the owner books 40 nights instead of 14 and uses the chalet personally for 30. The property is now a mixed-use rental, and expenses have to be allocated between the two buckets.
According to the University of Illinois Tax School, once personal use exceeds 14 days or 10% of the days rented at fair market rates, whichever is greater, the owner must report rental income and divide expenses proportionately between rental and personal days.
In practical terms, mortgage interest, property taxes, insurance, utilities, housekeeping, pool service, landscaping, and depreciation all get split. The rental share goes on Schedule E. The personal share lives on Schedule A, if it survives the standard-deduction math at all. The brochure line about the rental covering the carrying cost rarely accounts for the fact that only a fraction of those costs are actually deductible against the rental income.
There’s a second catch. On a mixed-use vacation property, deductions can zero out the rental income but generally can’t create a loss that offsets wages or other active income. The rental covers itself on paper and stops there.
The Bill Comes Due at the Closing Table
Fast-forward a decade. The chalet has appreciated handsomely, the family is ready to sell, and the owner assumes the primary-residence exclusion solves the capital-gains problem. It doesn’t, not on a second home, and not cleanly even if the owner moves in for a few years before selling. Two issues collide at the closing table:
- Nonqualified use. Years the property served as a vacation home or rental generally count against the portion of gain eligible for exclusion, even if the owner later converts it to a principal residence. The math is proportional, and on an appreciated luxury property it adds up fast.
- Depreciation recapture. Every year the owner claimed depreciation on the rental portion, the IRS was keeping score. Gain attributable to that depreciation is taxed separately at sale, often at a higher rate than the rest of the capital gain, with no residence exclusion available to shelter it.
- State treatment. States don’t follow federal rules uniformly on exclusions, recapture, or sourcing of gain on out-of-state property. The bill at the state level can be the surprise, not the federal one.
None of this makes the chalet a bad purchase. It makes the chalet a decision with downstream tax consequences that should be modeled before the first rental listing goes live, rather than reverse-engineered from a closing statement years later.
Decide What the Property Actually Is
The clean path is to decide up front which property the owner wants. A private residence with occasional tax-free rental activity under the 14-day ceiling. A mixed-use vacation home where rental income roughly covers its own expenses. Or an operating short-term rental business with the paperwork and participation to match. Each one has a defensible tax posture. The trouble shows up when the owner wants the lifestyle of the first, the cash flow of the second, and the deductions of the third, all against the same deed.
The chalet can pay for part of itself. It can also change what it is every time the calendar fills in. Knowing which version you own is the whole game.