A luxury car reveals a purchase, not the owner’s financial position. The same driveway could belong to someone with substantial savings or someone whose next paycheck already has a job. That ambiguity sits at the heart of displaying wealth versus structuring it, especially when visible spending attracts more attention than private financial decisions.
A driveway shows the car, but not its outstanding loan. Similarly, a large home reveals neither the mortgage balance nor the owner’s other financial commitments. These visible details leave much of the financial picture unexplained.
As spending becomes easier to display, building wealth remains harder to observe. The useful question isn’t who looks successful today, but what those financial choices leave behind after the attention fades.
The Short Answer: Display Spends, Structure Keeps
Displaying wealth turns money into visible purchases and experiences today. Structuring it organizes what remains to support future choices and obligations. The distinction lies less in how expensive a purchase looks than in what happens to the household’s finances afterward.
Economist Thorstein Veblen called status-driven spending “conspicuous consumption,” the formal term for flaunting wealth through purchases. However, appearances work both ways: Mark Zuckerberg’s plain wardrobe reveals no more about his finances than a designer wardrobe would about someone else’s.
Income is a flow over a period; wealth is the accumulated position at a particular point. A high salary can support expensive monthly commitments without leaving much behind. The two approaches aren’t opposites in income; they differ in where the money ends up.
For personal planning, the useful figure is a realistic resale estimate after selling costs, not the receipt. Treating the full purchase price as retained wealth confuses money spent with money still available. Saving and consumption serve different purposes, even when both involve expensive objects.
What Status Purchases Leave Behind
That difference becomes clearer years after a purchase, when the original price matters less than what remains. A possession might still provide enjoyment while offering little resale value. An asset held for financial purposes needs a different measure of success.
Why Most Display Purchases Lose Value Fast
A new car’s purchase price isn’t a reliable statement of its later resale value. Mileage, condition, and demand enter the calculation. Luxury fashion and jewelry introduce a similar distinction: the retail experience and brand premium aren’t necessarily recoverable when the owner sells.
Quiet luxury changes the visibility of the label, not this accounting. An understated designer coat remains a consumption purchase unless its resale proceeds actually support a different classification.
Quiet Stores of Value Like a 1oz Gold Bar
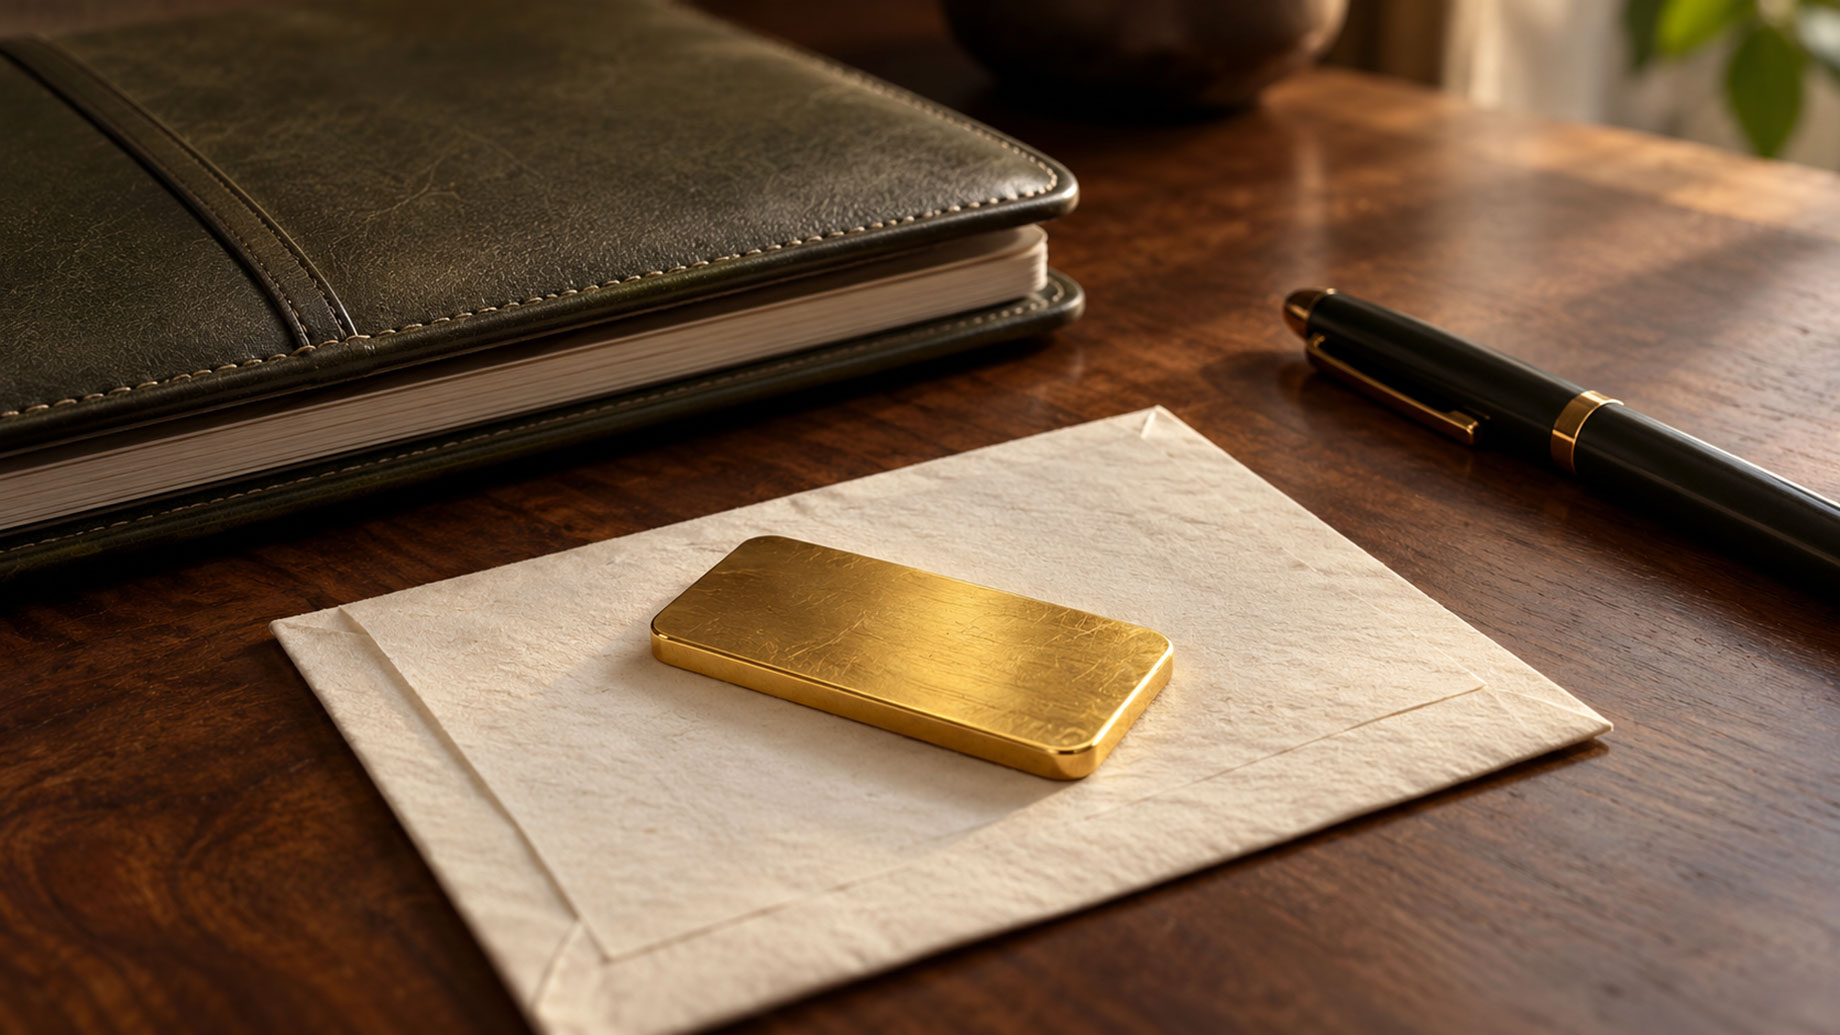
Physical bullion illustrates a different purpose: holding an asset rather than wearing a status signal. Its financial assessment centers on metal content and resale terms, not whether it completes an outfit. That doesn’t make gold a guaranteed safeguard or the only way to retain wealth.
Ownership also creates practical work. A fee-only planner assesses how much belongs in metal at all, a tax professional explains how bullion is taxed on sale, and on purity, storage, and delivery questions Monex account representatives can help.
Storage arrangements, insurance costs, and the gap between purchase and resale quotes belong in that assessment. Those details distinguish an ownership plan from a trophy purchase; none disappears because the asset stays out of sight.
Why a Big Lifestyle Rarely Means a Big Net Worth
As the purchase examples show, visible possessions tell only part of the story. Net worth means assets minus liabilities, not the total price of everything a household uses.
Income Signals Versus Retained Assets
Consider two hypothetical households starting with equal assets and debts. One earns more but spends its entire take-home income. The other earns less and consistently retains part of its pay. Before investment gains or losses, the second household adds to its financial assets while the first doesn’t.
The comparison isn’t a claim that lower earners always fare better. It isolates the deciding variable: the gap between income and spending. Flaunting wealth provides no dependable evidence of how large that gap is.
How Lifestyle Inflation and Debt Fund the Show
Lifestyle inflation occurs when higher earnings become higher recurring expenses. A raise disappears into a larger lease, a more expensive address, and upgraded habits. The household feels richer without increasing the amount it keeps.
An unchanged savings percentage can conceal this distinction. Savings may rise in cash terms while spending absorbs most of every additional paycheck, leaving future commitments dependent on the higher income continuing.
Debt adds another claim on that future income. A financed purchase creates both a possession and a repayment obligation; counting only the possession overstates wealth. Interest is an additional expense, and unpaid interest can itself attract interest where the borrowing terms allow it.
What Structuring Wealth Actually Involves
Financial structure consists of repeatable decisions that connect present resources with future obligations. It isn’t something a single impressive purchase establishes.
Wealth Management in Plain Terms
Wealth management means coordinating saving, investing, tax planning, protection, and estate decisions around the same purposes. Each part needs a defined job rather than a separate sales pitch.
For example, money reserved for an approaching expense shouldn’t depend on selling a long-term holding at a convenient price. Protection planning addresses losses the household couldn’t comfortably absorb. Ownership records establish what belongs to whom, while estate planning addresses intended transfers.
The practical test is whether the pieces agree. A plan that promises readily available money but ties everything up in difficult-to-sell assets contains a mismatch, regardless of the headline asset total.
Consistency and the Pull of Compound Interest
A regular contribution schedule turns saving into a recurring commitment rather than whatever remains after spending. Automation provides a mechanism for making that decision repeatedly, although contributions still need to fit actual cash flow.
The explanation of compound interest from the securities regulator shows how earnings can generate further earnings when they remain invested. Reinvestment gives accumulated returns a role in future growth instead of removing them for consumption.
That mechanism isn’t a promise of steady investment returns. Building wealth still requires attention to costs, losses, and access needs. Consistency concerns the contribution process; it doesn’t eliminate uncertainty about results.
Stewardship and What the Next Generation Inherits
Wealth stewardship extends the planning horizon beyond the current owner’s spending. It asks what the assets are meant to support and how another person would manage them.
That includes ordinary administrative details: an understandable record of holdings, clear ownership information, and an explanation of recurring obligations. An inheritance that’s difficult to identify or administer creates work before it provides useful choices.
Teaching heirs also means explaining decisions, not simply stating rules. Understanding why a family separates spending money from long-term assets gives the next generation a framework to use. Passing on values can’t guarantee preservation, but it gives heirs more than an unexplained collection of accounts and possessions.
Choosing What Your Money Is Meant to Do
Enjoyment isn’t the opposite of building wealth. A discretionary purchase can sit comfortably within an established plan. The dividing line is whether that spending follows provision for the future or takes its place.
A lifestyle describes how money gets used; a structure explains what it must continue to do.